Execution
The Supply Chain Squeeze: How Automakers Are Absorbing a Three-Front Cost War
Rising input prices and logistical friction are forcing executive teams to choose between margin erosion and aggressive pricing pivots.
Numerous Times Execution Desk
Operating playbooks that compound
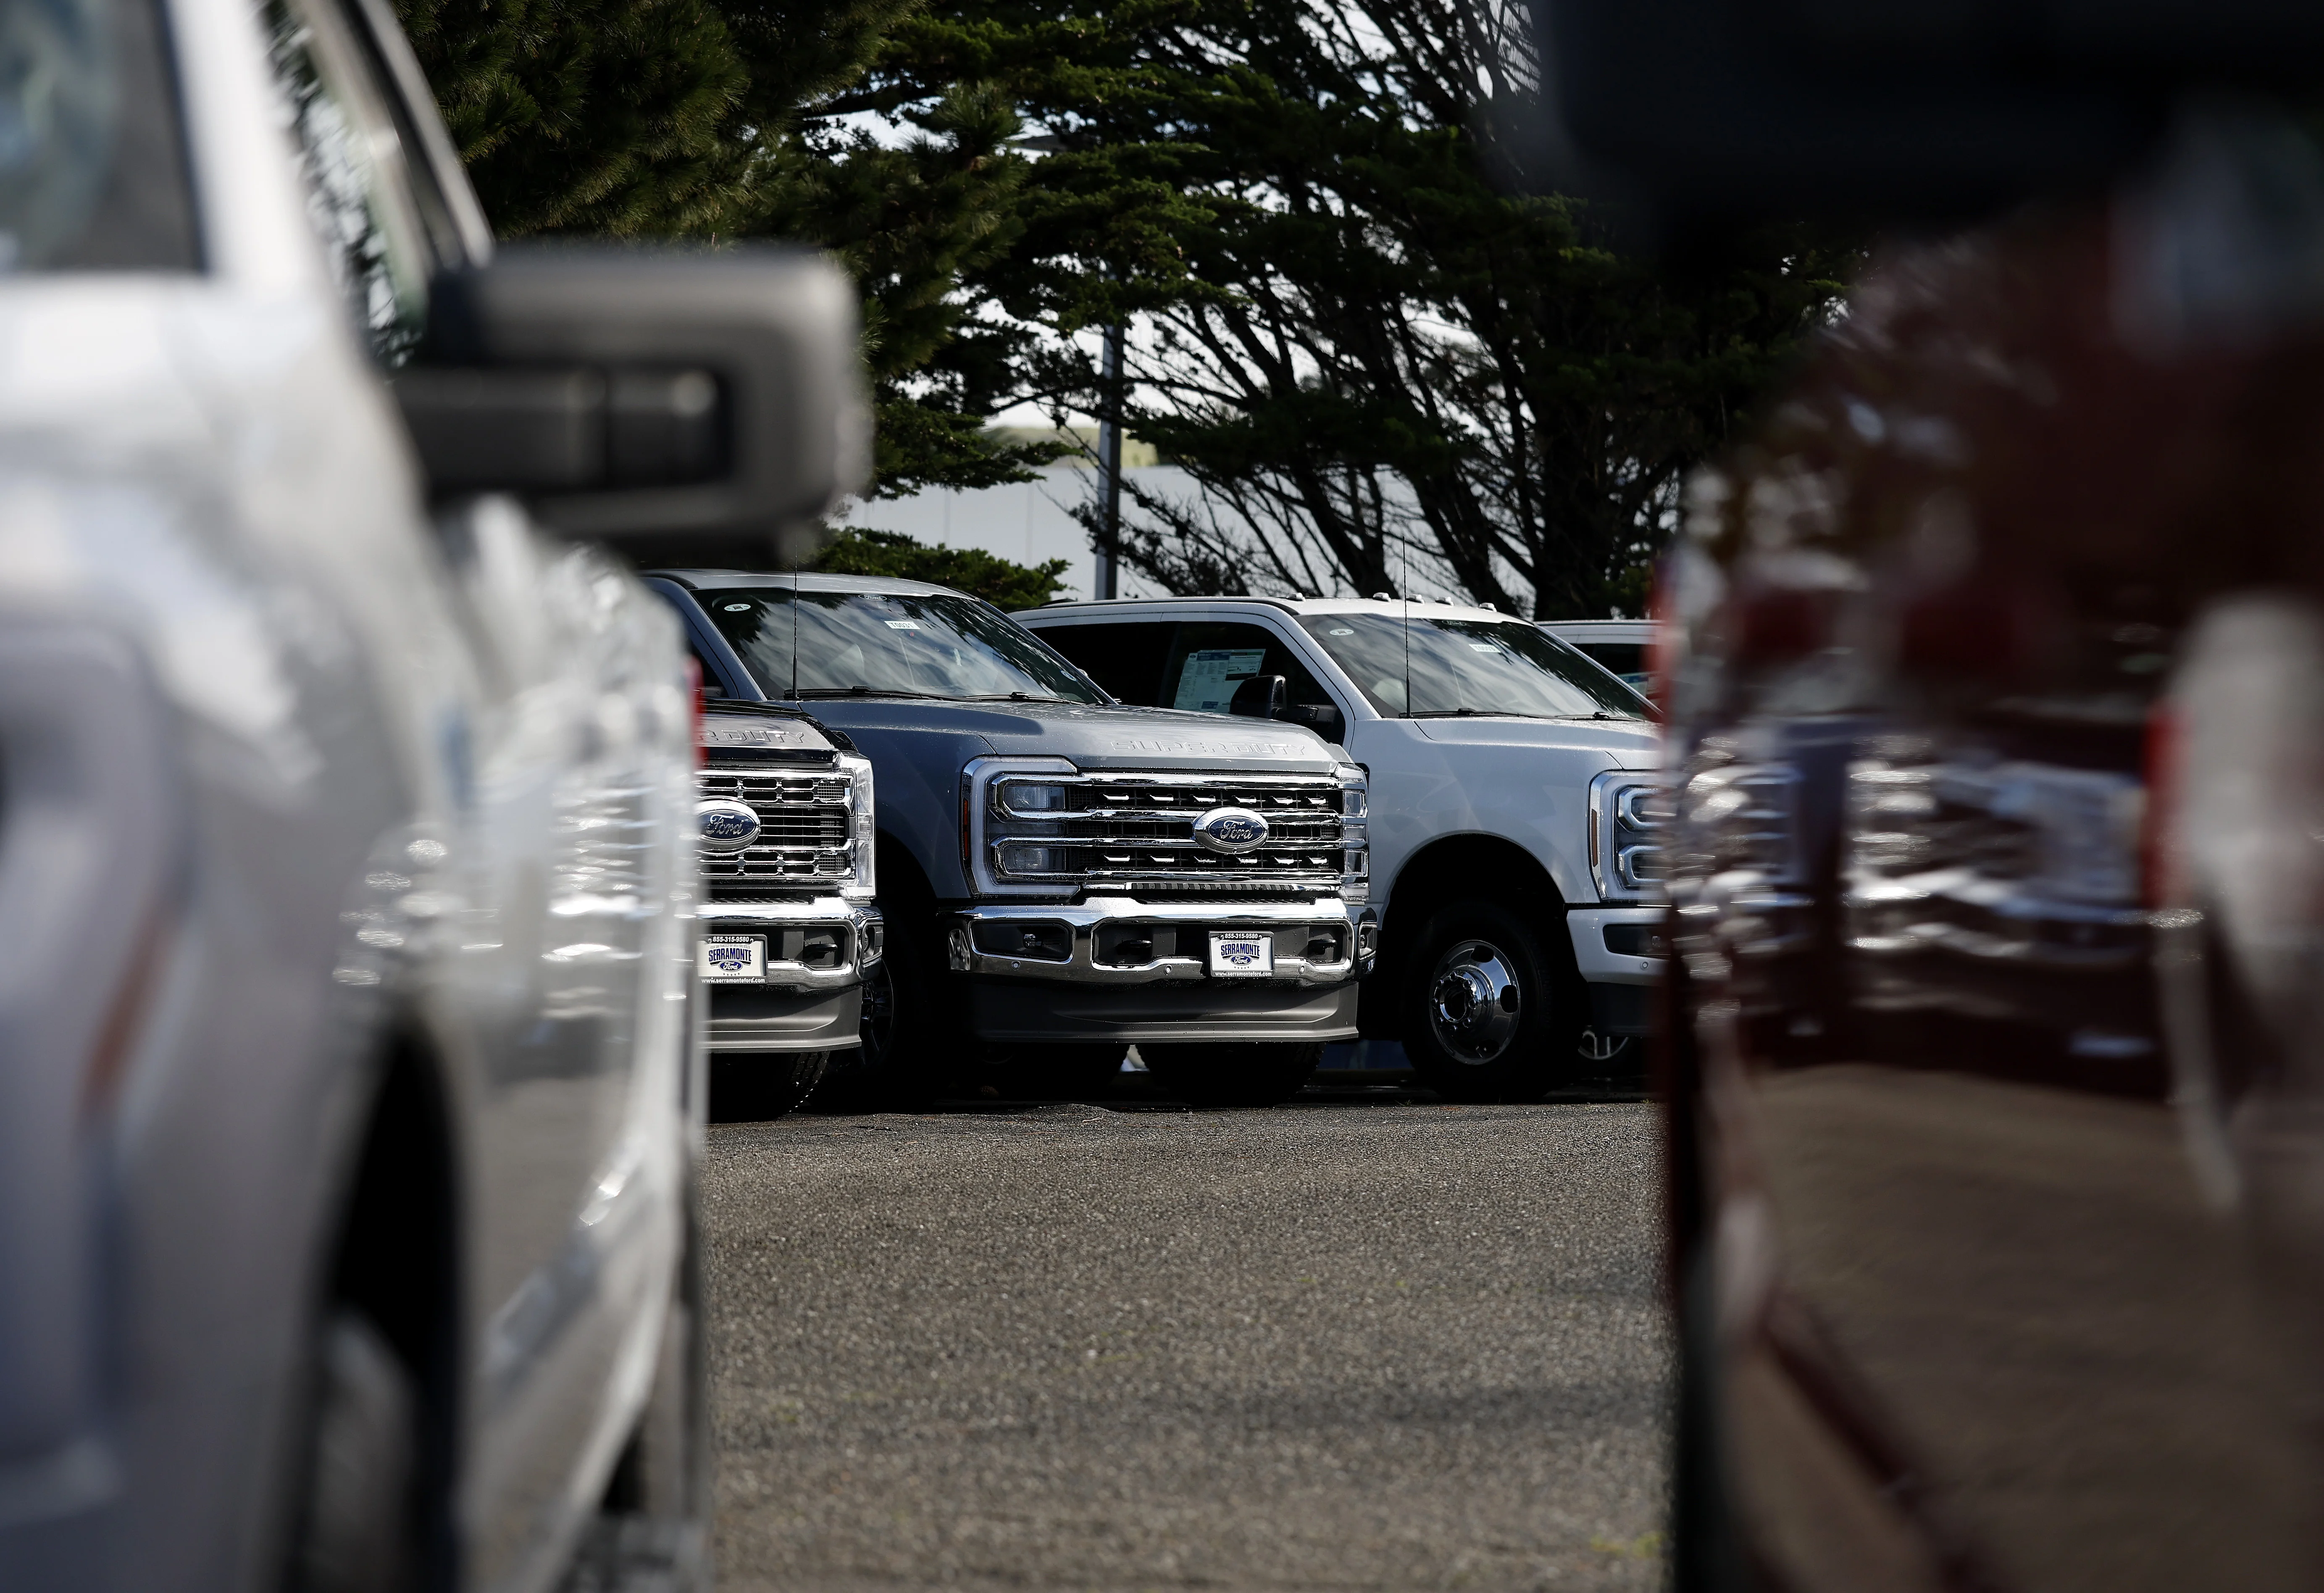
Detroit is currently navigating a convergence of inflationary pressures that threaten to stall the momentum of the manufacturing sector. Leading American automakers have signaled that the cost of doing business is climbing sharply, driven by a simultaneous spike in the price of raw materials, essential electronics, and the energy required to move finished vehicles from the factory floor to the dealership lot. This is not a localized glitch but a systemic escalation occurring across the domestic industrial landscape this quarter.
The current friction stems from a reliance on globally sourced components that have become significantly more expensive to secure. Steel and copper, the literal backbone of vehicle construction, are seeing volatile price swings that complicate long-term procurement contracts. Simultaneously, the persistent shortage of high-end computer chips continues to plague production lines. While the acute crisis of the pandemic era has subsided, the secondary effect is a permanent shift in the pricing power of semiconductor suppliers. When you compound these hardware costs with the rising price of diesel fuel used in heavy-duty logistics, the operational overhead per unit produced begins to eat into the historical margins automakers have enjoyed since 2021.
For an operations leader, this matters because it marks the end of the 'passed-through' inflation era. During the initial supply chain shocks of previous years, manufacturers could justify sweeping price hikes to consumers who were flush with cash and faced low inventory. Today, the market is more sensitive. Automakers can no longer simply raise the MSRP without risking a drop in volume. This creates a high-stakes execution challenge: companies must find internal efficiencies—reducing waste in the assembly process, renegotiating tier-two supplier contracts, or optimizing logistics routes—to offset the hundreds of dollars in new costs added to every vehicle.
In the coming months, the industry will be watching for two specific indicators. First is the shift in inventory management strategies; look for companies to move away from just-in-time delivery toward strategic stockpiling of volatility-prone metals. Second is the potential for 'de-contenting,' where manufacturers may begin removing non-essential electronic features from base models to preserve their margins on high-volume units. If the price of diesel and raw materials does not stabilize by the next fiscal quarter, expect a more aggressive consolidation of supplier networks as manufacturers seek to shorten their supply chains and gain better control over the total landed cost of their components. The era of cheap precision manufacturing is being replaced by a period where the winner is the one who manages the unglamorous math of the freight bill.
One essay. Every Friday. From operators who actually run things.
Join thousands of founders, partners, and operating leaders. No filler. Unsubscribe anytime.
Reader notes
0 NotesSign in to comment. Comments are signed and public.
Sign in →