Execution
The Physics of Wealth Flight: Calculating the True Cost of State Wealth Taxes
As California weighs a landmark tax on the ultra-wealthy, the real debate isn't about fairness, but the mechanical reality of how mobile capital responds to new costs.
Numerous Times Execution Desk
Operating playbooks that compound
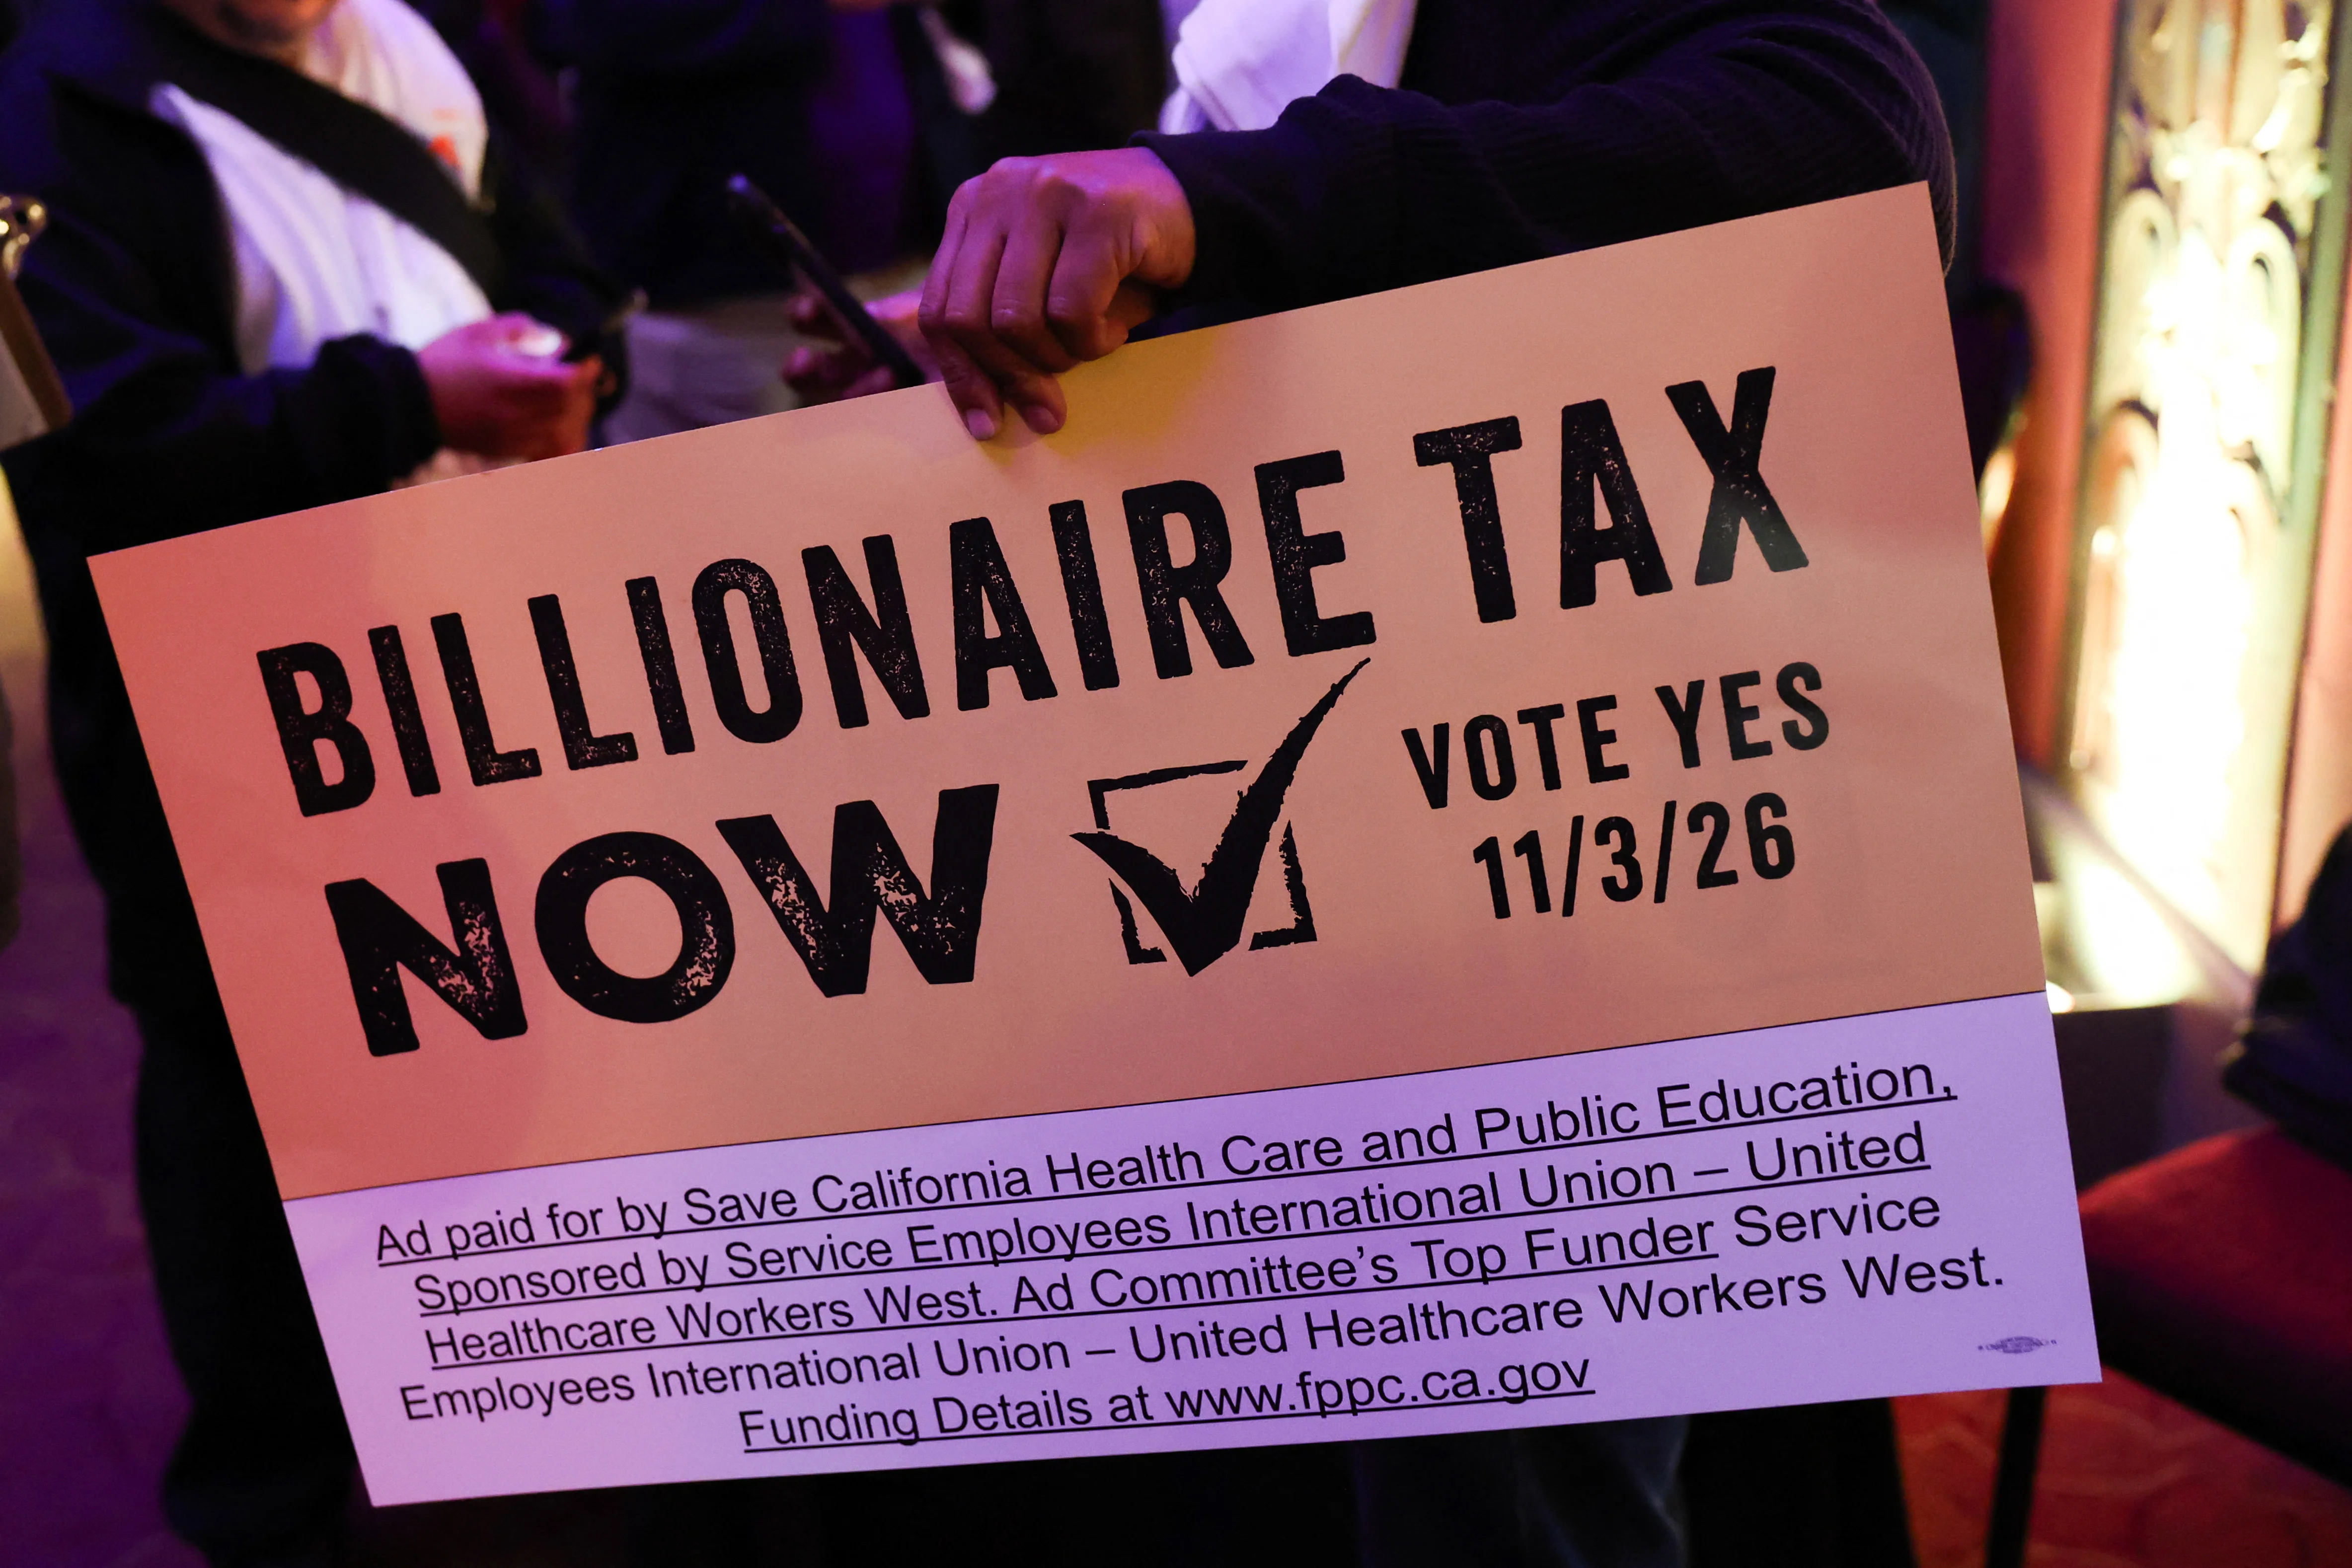
California is currently the staging ground for a high-stakes legislative experiment that could fundamentally alter the fiscal mechanics of the American state. A proposed tax targeting the state's wealthiest residents has moved to the center of a heated debate between policymakers looking to shore up budget deficits and economists trying to predict the breaking point of human mobility. The policy aims to levy an annual tax on the net worth of billionaires, extending even to those who have recently left the state, creating a jurisdictional tether that is as legally ambitious as it is economically controversial. At its core, this is a test of whether a single state can successfully tax unrealized wealth without triggering a mass exodus of the very capital that fuels its innovation economy.
The history of such wealth taxes is littered with cautionary tales from European nations that attempted similar schemes in the late twentieth century. Most of those countries eventually repealed the measures after discovering that the administrative costs and the subsequent flight of wealthy citizens outweighed the revenue generated. California, however, believes its unique concentration of technology giants and venture capital creates a 'sticky' environment that might defy historical trends. Proponents of the bill argue that the state’s cultural and professional infrastructure provides a value proposition that justifies the increased cost of residency. This creates a fascinating tension between the social contract and the cold calculus of individual balance sheets.
For the executive desk, the importance of this development lies not in the political optics, but in the precedent it sets for capital allocation and corporate relocation. If passed, the tax would force a mandatory annual valuation of non-liquid assets, including private equity holdings and intellectual property, which are notoriously difficult to price. This introduces a significant administrative burden for both the state and the taxpayer, requiring a new army of auditors and appraisers to settle disputes over the value of companies that haven't yet gone public. For founders and early-stage investors, the mechanic of the tax could necessitate selling off portions of their holdings just to cover the annual tax bill, potentially diluting their control over their own enterprises.
Two competing economic analyses have emerged to predict the outcome of this policy, and their disparity reveals the fundamental uncertainty of the project. One study suggests that the tax would be a windfall, generating billions in stable revenue that could fund public services and bridge the state's recurring budget gaps. This perspective assumes that the ultra-wealthy are largely immobile due to their deep-rooted business interests and family ties within the state. It views the tax as a small price to pay for access to the California market and its unparalleled talent pool. In this model, the friction of moving—finding new schools, relocating headquarters, and leaving a specific social ecosystem—is higher than the cost of the tax itself.
A second study presents a far darker forecast, suggesting the tax could lead to a net loss for the state treasury. This analysis emphasizes the high elasticity of the ultra-wealthy, arguing that the mere threat of a wealth tax serves as a powerful incentive to relocate to tax-friendly jurisdictions like Texas or Florida before the law even takes effect. Because a small number of taxpayers contribute a disproportionate share of California’s total income tax revenue, even a minor migration of billionaires could result in a collapse of the existing tax base. From an execution standpoint, the risk is that the state trades a reliable stream of high-income tax for an unreliable and difficult-to-collect wealth tax.
The mechanical challenge of implementing a wealth tax also involves the 'exit tax' provision, which attempts to claim a portion of a resident's wealth for years after they have moved away. This provision is designed to prevent tactical relocation just before a liquidity event, such as an initial public offering or a company sale. However, the legal enforceability of one state reaching into another state's jurisdiction to tax a non-resident is a murky area of constitutional law. If the courts strike down these tail-end provisions, the entire fiscal logic of the bill could crumble, as it would essentially provide a roadmap for how and when to leave the state to avoid the levy.
Operational leaders must watch how this affects the broader talent pipeline and the location of new corporate headquarters. If California proceeds, we are likely to see a shift in how executive compensation is structured, with a move away from massive equity grants that trigger wealth tax thresholds toward more creative, perhaps deferred, forms of value accumulation. We may also see an acceleration of 'hq2' strategies, where companies maintain a nominal presence in California while moving their primary legal and financial operations to states with more predictable tax regimes. The unglamorous reality of tax planning will become a primary driver of corporate strategy for any firm with a high-net-worth cap table.
Beyond the immediate fiscal impact, the California experiment serves as a bellwether for federal policy. If the state manages to implement the tax without a catastrophic loss of its tax base, it will provide a powerful proof of concept for similar proposals currently stalled in Congress. Conversely, if the policy triggers a visible flight of capital and a subsequent credit downgrade for the state, it will likely kill the prospect of a national wealth tax for a generation. The execution of the valuation process will be the critical variable; if the state cannot accurately and fairly price private assets, the resulting litigation will paralyze the system regardless of how many billionaires stay put.
In the coming months, the most important indicators to track will be the rate of luxury real estate listings in key California zip codes and the filing patterns of new venture funds. While public statements from billionaires often lean toward the dramatic, their actual movements and the restructuring of their holding companies will tell the real story. The state’s ability to defend the legality of taxing former residents will also face immediate challenges in the court system. If the wealth tax survives its first legislative and legal hurdles, the playbook for American fiscal policy will be rewritten in real-time, forcing every high-growth company to re-evaluate the cost of doing business in the Golden State.
One essay. Every Friday. From operators who actually run things.
Join thousands of founders, partners, and operating leaders. No filler. Unsubscribe anytime.
Reader notes
0 NotesSign in to comment. Comments are signed and public.
Sign in →